

Private wealth buyers snap up Asia, Europe real estate
Fri, 9th Oct 2026 (Today)
Private wealth investors are increasing their commercial real estate activity across Asia Pacific and Europe, with quality assets in several markets trading below replacement cost, according to JLL.
The shift follows a broad repricing in commercial real estate, with private investors moving faster than many institutional buyers. Across core markets in Asia Pacific and Europe, higher construction and labour costs have pushed the cost of developing new buildings above the price of some existing assets.
Private capital has been the largest source of funding for commercial real estate globally for four consecutive years, JLL said. In Asia Pacific, private capital investment rose sharply even as overall investment activity declined.
The largest increases were in Hong Kong, where private capital investment rose 40%, Singapore 93%, South Korea 237% and India 1,378%. Japan also remained a major focus across several property types.
In Europe, markets moved earlier in the repricing cycle. The UK, France and Germany are now offering quality assets at substantial discounts to previous peaks and below current construction costs, according to JLL.
The UK attracted more than EUR €10.1 billion in private investment last year, up 66% from 2024. London accounted for EUR €5.2 billion of that total, more than double the volume recorded a year earlier.
Cost pressures
The report points to construction economics as a growing part of investment analysis. In Asia Pacific, rising delivery costs for new prime office towers have pushed replacement values well above current acquisition prices for quality existing buildings in some cities.
Sydney was highlighted as one example, with the cost of building new prime office stock now exceeding the price of acquiring comparable standing assets. Tokyo, by contrast, offers more selective opportunities in older buildings that may require repositioning.
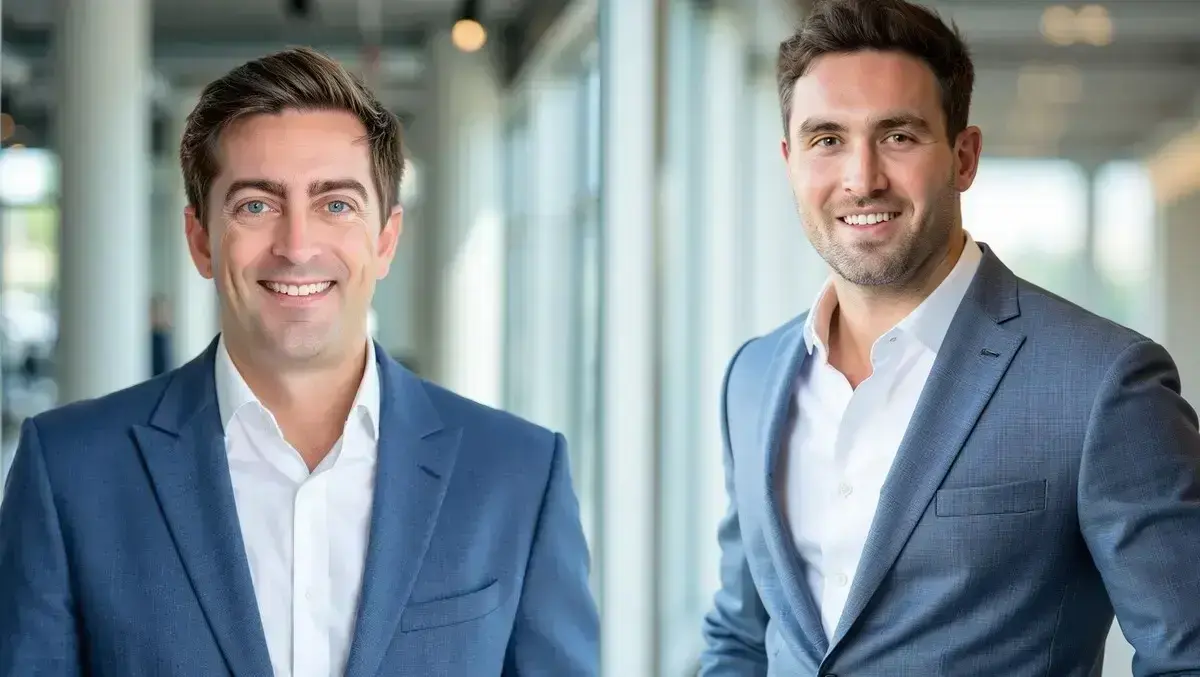
"Rising construction and labour costs are being closely monitored by investors, in addition to the rate environment," said Tim Graham, Global Lead, International and Strategic Capital, Head of Private Wealth in APAC at JLL.
"That's a bullish signal for existing well-located assets, because constrained supply creates rental growth potential in markets where occupier demand is healthy," Graham said.
Limited new supply is becoming more important in markets where occupier demand remains firm. For investors, that means existing buildings with income in place may look more attractive than developments requiring higher upfront spending.
"The construction cost dynamic is now explicitly part of buying decisions in Asia-Pacific in a way it wasn't eighteen months ago," said Daniel Billig, Senior Director, Capital Markets Transactions at JLL.
"When investors compare the economic costs of development against the option of acquiring income producing assets with minimal capex, the acquisition case becomes much easier to make," Billig said.
Buyer advantage
Private wealth investors are often winning deals on execution speed and certainty rather than on price alone. Those buyers tend to have clearer decision-making processes and face fewer approval hurdles than institutional investors, which are often constrained by longer internal processes and performance pressures.
That has helped private wealth buyers compete for both trophy assets in gateway cities and mispriced properties that can be improved and sold after a holding period of several years. JLL said these are the two main approaches being pursued by this pool of capital.
In Europe, discounts from earlier market peaks are central to the investment case. Some assets are trading about 20% to 30% below prior highs, drawing interest from investors assessing value over a longer time frame.
"If you're looking at an asset that is currently trading at a discount of around 20-30% compared to previous peaks, then on a long-term basis that represents good value, and when combined with future rental growth and solid fundamentals, then that's a pretty mitigated risk," said Joseph von Maltzahn, Head of Private Wealth for EMEA at JLL.
"When you couple that with the question 'what would it cost to replace this building today?' and the answer is more than you're paying, your downside is well protected," von Maltzahn said.